More Americans see better economic days ahead, giving merchants an opening to win purchases that cautious households have put off.
That’s one encouraging finding in “Keeping Up Gets Harder: Debt Confidence Falls Among Bill Payers,” the October 2026 PYMNTS Consumer Expectations Index report. Based on a survey of 2,087 U.S. consumers conducted Oct. 1–13, the report finds that economic expectations improved even as job worries increased and confidence in managing debt weakened. The overall index edged up to 54.2 from 54.1, ending two consecutive monthly declines. Consumers’ brighter outlook offers businesses some encouragement, but household budgets still set the spending limits.
Key Points:
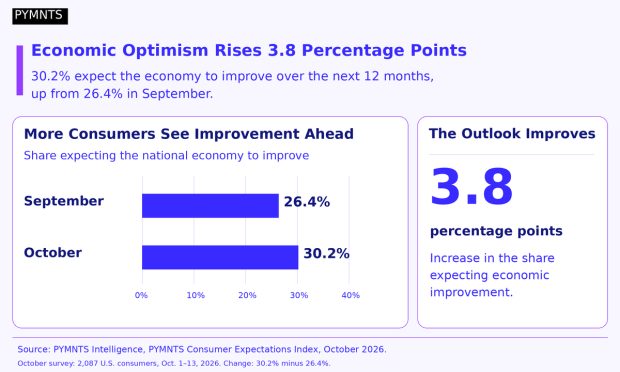
- More consumers expect the economy to improve. The share anticipating improvement in the national economy over the next 12 months rose to 30.2% from 26.4% in September, a gain of 3.8 percentage points. The report’s measure of economic outlook and buying conditions increased 1.8 index points to 46.8. All three components improved, covering short-term business conditions, longer-term expectations and buying conditions. Still, the combined reading remained below the neutral midpoint of 50, indicating that the improvement hasn’t eliminated consumers’ reservations.
- Major purchases look more appealing, though delays persist. The share saying it was a good time to make a major household purchase reached 25.5%, up 2.7 percentage points from September. Consumers living paycheck to paycheck and struggling with bills recorded the strongest improvement in buying conditions, although their score remained the lowest among the three financial groups. Meanwhile, 20% of consumers said they’d delayed a major purchase during the previous 90 days, compared with 18.3% in August. Another 11.1% reported canceling a major purchase, up from 9.6%. Respondents could select more than one action.
- Price gives merchants a clear place to start. Among consumers who traded down, delayed or canceled a major purchase, 34.9% named high prices as the main reason. Waiting for a better deal or better timing followed at 17.6%. That distinction suggests different opportunities: promotions may persuade shoppers who can afford to wait, while lower-priced choices may better serve households with less room in their budgets.
Other findings help explain why improving expectations haven’t translated into an equally clear spending recovery. Among paycheck-to-paycheck consumers who could pay their bills without difficulty, confidence in managing debt fell to 61.1% from 71.2% in September. There was also some relief: across all consumers, the share saying their savings would last three months or less declined to 47.5% from 51.8%. For merchants, the opportunity lies in making purchases affordable enough for improving sentiment to support actual spending.
At PYMNTS Intelligence, we work with businesses to uncover insights that fuel intelligent, data-driven discussions on changing customer expectations, a more connected economy and the strategic shifts necessary to achieve outcomes. With rigorous research methodologies and unwavering commitment to objective quality, we offer trusted data to grow your business. As our partner, you’ll have access to our diverse team of PhDs, researchers, data analysts, number crunchers, subject matter veterans and editorial experts.